


Join My Community
Join 10,000+ entrepreneurs receiving proven strategies and the best opportunities delivered straight to their inbox.

Happy Wednesday!
Many people spend years thinking about buying a business without ever actually doing it.
They’re waiting for more savings, more stability, or the “perfect” moment.
The problem is that moment rarely arrives on its own, and the longer you wait for it, the more opportunity passes by.
So instead of asking whether the timing feels right, here are the first two questions worth answering. 👇

Kris bought a $2.6M oil field service company while keeping his full-time job at Chevron, and he’s now making $250K/year in passive income.
“The value that I got out of Acquisition Ace is learning all the definitions, learning what to say, how to deal with the banker, how to deal with the lender. I wouldn’t have any of that stuff had I not joined this group. I’m making a lot more money now than I’ve ever made.”
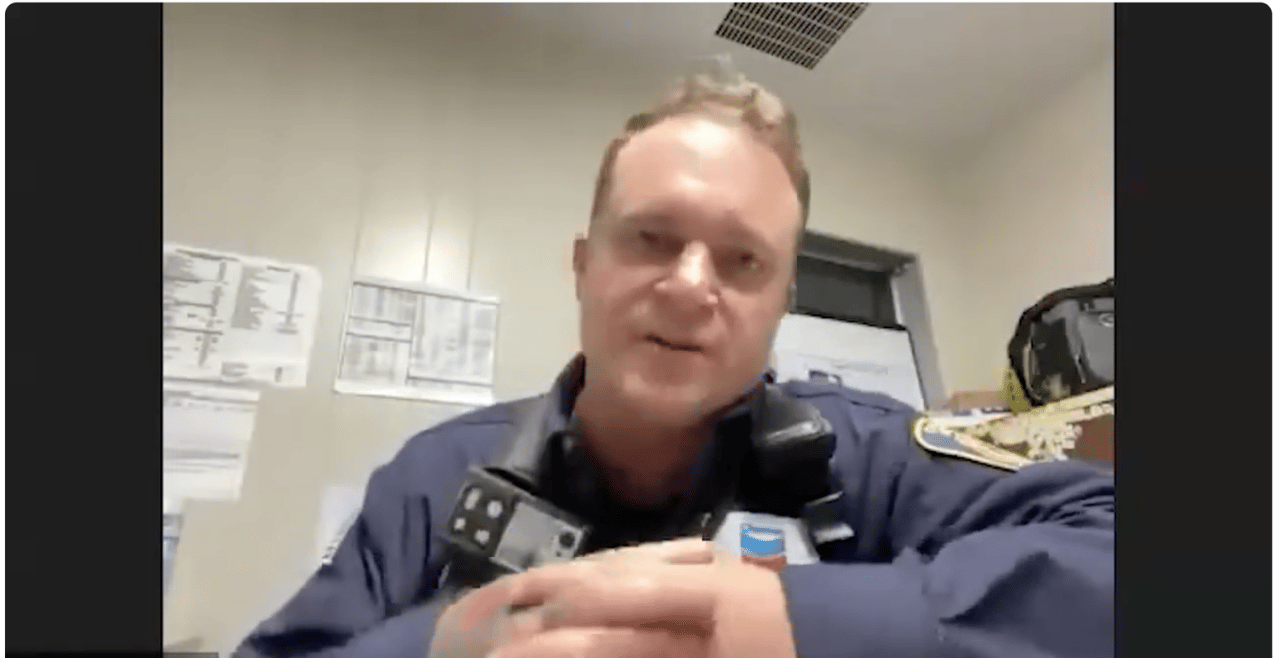
He went from knowing nothing to closing a multi-million dollar deal in 5 months.
👉 Want to learn exactly how to navigate lenders and close your first deal? Book a call with our team here.
Do you meet the financial baseline?
You don’t need to be wealthy to buy a business.
But you do need to understand what lenders are looking for before you start searching.
The clearest first step is getting pre-qualified with an SBA lender.
Bring your last three years of tax returns, recent pay stubs, and a personal financial statement.
A lender will tell you exactly what you can afford, and what, if anything, you need to address before applying.
As a general rule, expect to need roughly 10% of the purchase price as an equity injection, either from your own capital or from an investor.
On a $1M business, that’s $100K.
That number can be structured creatively, but it needs to be there in some form.
If you’re not at that level yet, that’s a useful and honest answer.
Build toward it with a clear target in mind rather than vaguely waiting to feel ready.
(Inside Acquisition Ace, members get connected with vetted SBA lenders early, so they know their real buying power before falling in love with a deal they can’t fund. To see how our community can help with your acquisition, book a call with our team here.)
Can you commit one focused hour a day?
You don’t need to quit your job or clear your calendar to find and close a deal.
Most people who’ve gone through this process were working full-time and managing real family responsibilities while they did it.
What matters is consistency.
One focused hour per day, sustained over six to nine months, is enough to build deal flow, develop your evaluation skills, and get to a closed transaction.
If you can protect that hour consistently, you have the time.
Tomorrow, I’ll cover the two questions that are harder to answer, but just as important before you commit to this path.
If you’d like to start building toward this with a clear framework, the Acquisition Ace community is a great place to begin.
👉 Book a call with my team here to see if it’s a good fit.
 | Onward, Ben Kelly PS: Check out our latest YouTube video. We reveal how one entrepreneur built a multi-million dollar pool company from scratch with no industry experience. |


