


Join My Community
Join 10,000+ entrepreneurs receiving proven strategies and the best opportunities delivered straight to their inbox.

Happy Wednesday!
Yesterday I covered the foundation of a good LOI: how to structure the purchase price and why exclusivity is so important.
Today I’m covering additional elements that are also crucial: the assets, contracts, and people that need to be documented before due diligence begins, and a term that can bridge a price gap when you and the seller aren’t quite aligned.

Leann bought a $1.3M sign company after joining Acquisition Ace, and her son now runs operations.
“We learned a ton out of the gate through Acquisition Ace. We appreciated the camaraderie in the group. We appreciated the openness. We appreciated the information. We wouldn’t have gone down this road without going through your program because we just didn’t know enough.”
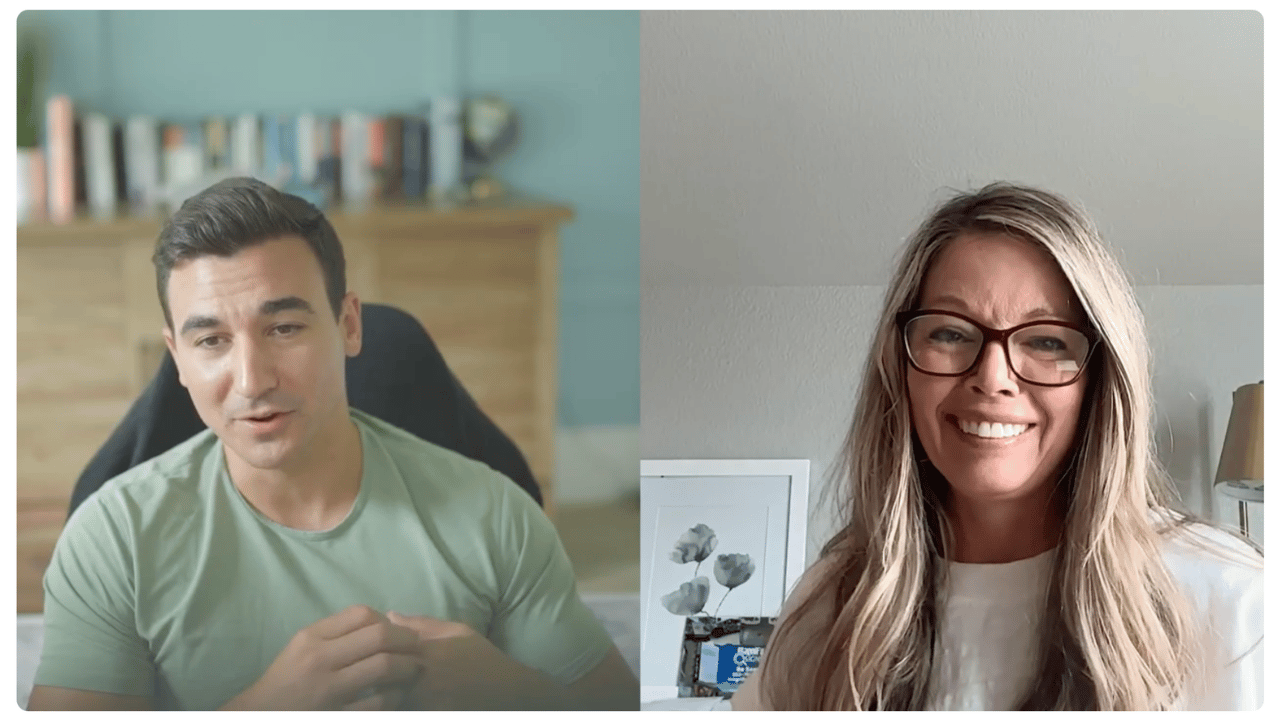
She went from program manager to business owner in less than a year.
👉 Want the foundation and knowledge to confidently pursue your first acquisition? Book a call with our team here.
Key assets, contracts, and people
The LOI should document your expectations around the things that directly affect cash flow after you take over.
Which client relationships are expected to transfer, and are there any that might leave with the seller?
Which supplier contracts carry over, and on what terms?
Who on the current team is staying, for how long, and at what compensation?
Getting alignment on these details upfront prevents last-minute surprises that kill deals.
A seller who says “we’ll work out those details later” is a seller who hasn’t fully committed to the terms of the deal.
(Inside Acquisition Ace, members learn how to use the LOI stage to lock in important terms before spending weeks on due diligence. To see how our community can help with your first deal, book a call with our team here.)
Performance-based terms
If you and the seller are apart on price, a structured seller note can sometimes bridge the gap without either side fully conceding.
One approach that works well: a seller note that’s partially or fully forgivable if the business underperforms against agreed benchmarks in the first year or two after closing.
It protects your downside if the business doesn’t perform the way the seller represented, and gives the seller a reason to ensure a smooth, cooperative transition rather than just cashing out and disappearing.
This structure works particularly well when the seller is confident in their numbers.
If they believe the business will perform, they’ll likely agree to the terms.
The bigger picture
Every term you leave vague in the LOI is a conversation you’ll have to have again later, under more pressure, with less leverage…
And potentially after you’ve already invested significant time and money into the process.
Sellers who are serious with LOIs will engage with it seriously.
The ones who want to stay vague on key terms may be protecting something you’d want to know about before committing.
If you'd like support through all stages of dealmaking, the Acquisition Ace community is the perfect fit.
👉 Book a call with my team here and let’s talk about how our community can help you in your path to business acquisition.
 | Onward, Ben Kelly PS: Check out our latest YouTube video. We reveal how one entrepreneur built a multi-million dollar pool company from scratch with no industry experience. |
This is the tool I use to find deals: SMBMarket.com


